The EDF Backlash Is a Symptom of a Bigger Systemic Silos Problem in Government

EDF Backlash

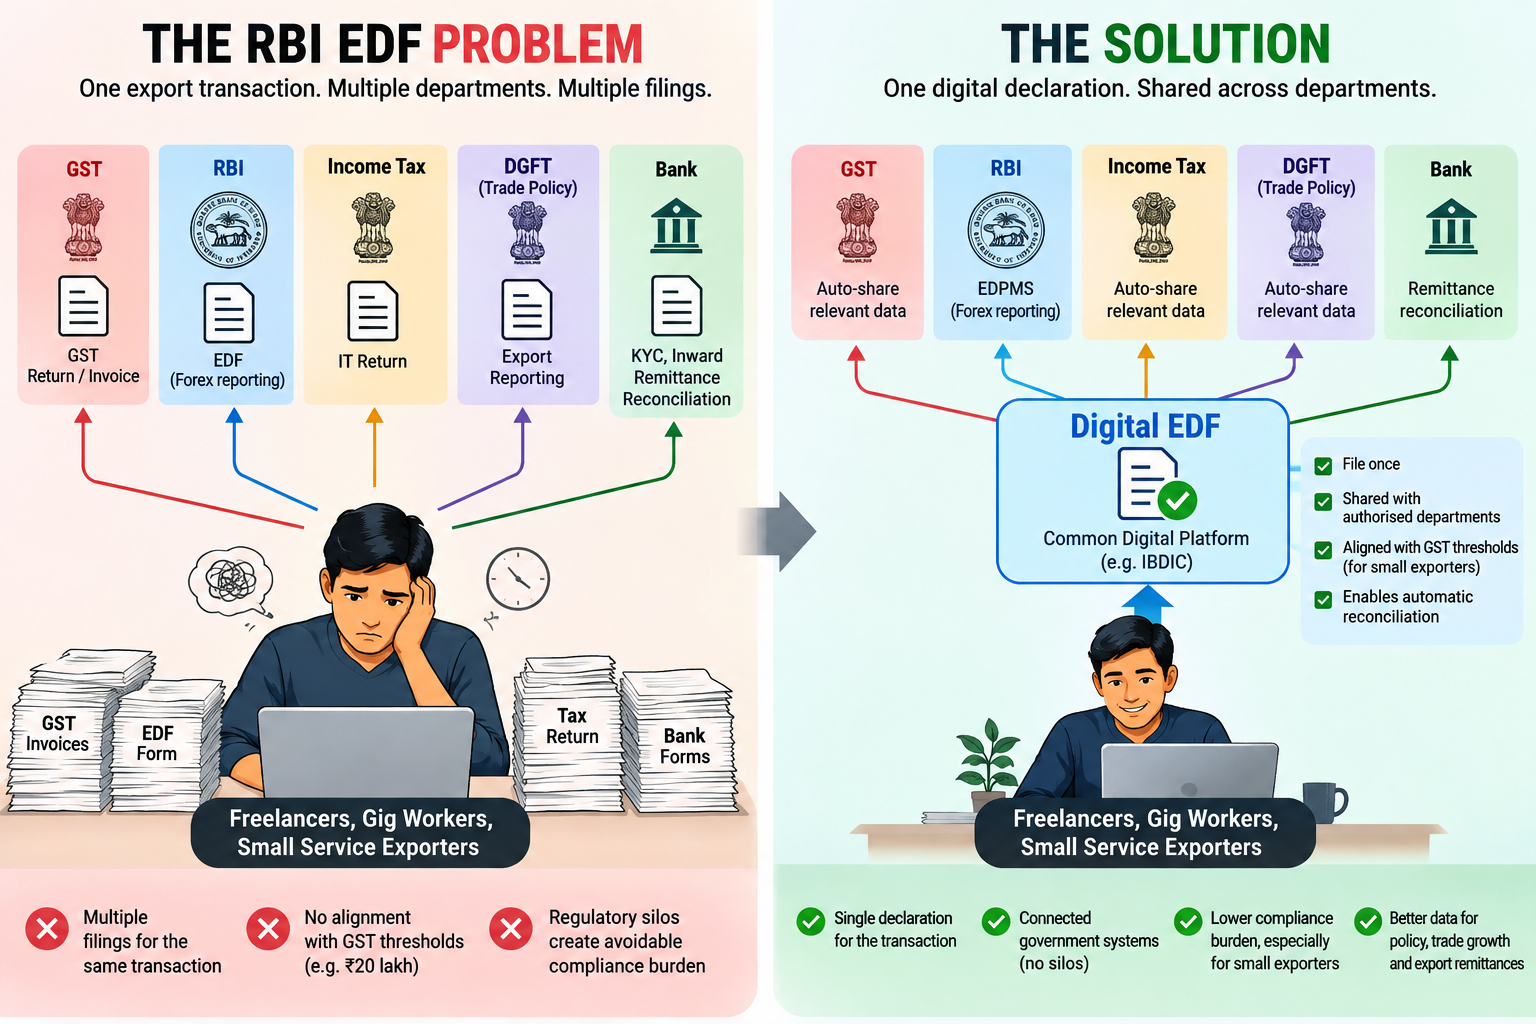
There is a strong backlash over the Reserve Bank of India’s new Export Declaration Form (EDF), particularly from freelancers, gig workers and small service exporters, which deserves attention, not simply because of the compliance burden it may create, but because it exposes a larger problem in how the government regulates the economy.

The EDF form is an export declaration form under RBI’s Notification No. FEMA 23(R)/2026-RB, January 13, 2026. This notification was announced to remove Softex form and make export declaration f uniform across Software and other services. However, it resulted in trapping small exporters who were not filing Softex earlier becuase they were not exporting Software or were exporting Software that falls in to P802 purpose code. Many of these are Gig Workers (Freelancers) doing small exports and receiving foriegn exchange either directly or through some freelancer aggregator platform or from content platforms. All these were in some form providing data to RBI when remittance acceeptance and purpose code declaration is done. Hence, introduction of one more filing requirement in form of EDF created uproar in this category of exporters. This category may be small in export size but important for Gig economy.

An exporter does not operate under FEMA alone. Had RBI considered the other laws affecting exporters of all sizes, from smallest to largest, before preparing this new FEMA notification, the problem would not have arisen. 

This is not an argument against regulation. RBI has a legitimate responsibility to monitor foreign exchange and export realisation. But regulation designed in isolation can create unintended compliance costs and, more importantly, undermine the larger government’s Ease of Doing Business objective. 

The systemic problem is that one regulator does not consider or interact with other regulators. 

RBI can adopt a simple solution to the EDF problem

In the short run, RBI can consider exempting small exporters earning below 20 lakhs from GST registration. For exporters earning above 20 lakhs, RBI (through IBDIC) should create a digital EDF on common infrastructure, accessible to authorised banks and relevant government systems, with the necessary information flowing into EDPMS.

In the long run, everyone should be brought under this data capture and not abandon EDF. But make its implementation fully digital. For goods, exporters submit to ICEGATE; the EDF is auto-generated from the submitted data. Similarly, for Services and Intangibles, EDF can be auto-generated from data submitted by exporters to 

  1. From GSTR-1, from data submitted to GSTN for those registered with GST Or
  2. Banker at the time of remittance for those not registered with GST

This would also solve a problem for banks. Banks ultimately need to reconcile export proceeds and close the transaction in the regulatory system. If the export declaration, payment and realisation information are digitally connected, much of this reconciliation can move from manual compliance to straight-through processing.

The principle is simple: Declare once. Reconcile automatically. Share the information with every authorised government consumer.

Ensuring cross-regulatory sanctity and ease of doing business.

The exporter sees one transaction. The government sees multiple regulatory transactions because each department sees the transaction through its own statute.

The larger lesson from the EDF episode is that whole-of-government cannot mean merely asking departments to coordinate after a regulation has been designed.

Whole-of-government must begin at the design stage of regulation itself.

Before creating a new compliance requirement, the regulator should ask: Which other laws apply to this transaction? Which other departments regulate it? What thresholds already exist? What information has already been submitted? Which government system already holds it? Can the new requirement be fulfilled through an existing digital system rather than through another form?

These questions should become part of the regulatory design process.

The EDF episode is therefore a small but important warning.

Government must stop designing regulation department by department when businesses operate transaction by transaction.

The next generation of Ease of Doing Business will not come merely from removing regulations. It will come from making different regulations work together.

For this, the Government must pursue a Unified Digital Trade system. This requires a genuine whole-of-government approach—and, eventually, the Connected Digital Public Infrastructure (Digital Port) to make it possible.
EDF replaces Softex form. Your Bank can Certify Software Exports from October 01, 2026 

We had published a Blog in 2016 on Sofex form confusion. It became one of the most-read pieces on our blog. Read here for ready reference.

Since then, we have been exhorting the Government to remove the Softex and, more specifically, after GST came into existence. Softex forms have been replaced by RBI in a recent notification with a single form called the Export Declaration Form (EDF), for both Goods and Services. This Blog helps you decipher the Gazette Notification No. FEMA 23(R)/2026-RB given here (Click to read) dated 13 Jan 2026.

While we have been advocating for bold reform by the RBI and related foreign trade regulators, the RBI has delivered only on one part. A 100% digital transformation of regulatory systems could help India move from the 6-7% growth bracket to the 9-10% growth bracket. Unfortunately, the current policy step misses this opportunity. We hope there will be corrections to adopt a bold stance soon. 

We have analysed below what this current notification has in store for the exporters in the Software or Services sector from October 01, 2026, the date when this notification comes into force.

What does it mean for the software sector?

Is Softex abrogated?

The Softex form will not exist from 1st October 2026, but the export declaration will remain. RBI has mandated one single form known as the export declaration form (EDF). All goods and services (including Software) exporters will file EDF forms.

Is it still mandatory to get STPI certification?

RBI, through this notification, now recognises Authorised dealers as “Specified Authority” at par with STPI in DTA. Hence, STPI certification will not be mandatory, and Software, IT, or ITeS businesses in DTA will have the option to get it certified by bankers after 1 October 2026.

However, if an authorised dealer, i.e. your bank, wants STPI or SEZ to certify, then it may not be possible to bypass STPI. So this remains to be clarified after the banks notify their process, as the RBI has left the process to the banks.

Software definition

RBI has issued an interim relief earlier, asking IT-Enabled Services to be exempted from STPI /SEZ certification and to directly file with banks under the purpose code P802. This relief had come very recently, less than a year ago. Why code 802 came into existence is not known in the public domain.

The notification defines “Software” as “any computer programme, database, drawing, design, audio/video signals, any information by whatever name called in or on any medium other than in or on any physical medium.”

It is a very ambiguous definition, and it seems to include everything intangible. Effectively, this means only services that are delivered physically onsite in a cross-border geography will be out of the scope of this definition. After this notification, the distinction between Software, IT Services, and IT-enabled services will vanish. There is no clarity in the use of the purpose code in the notification. Perhaps this will evolve into standard operating procedure by banks in future and remove some of the anomalies.

It would have been better to accommodate this for the clear classification and separate purpose code for the following, or a way to map it with HSN and Service Accounting Code (SAC) as used by CBIC.

What and who is a specified Authority?

The notification does not define ‘specified officer’ but names them. The way this is defined will still keep some confusion alive.

(i)  Commissioner of Customs in the Domestic Tariff Area (DTA) and Development Commissioner of Special Economic Zone (SEZ) in SEZ, for goods;
(ii) An Authorised Dealer in DTA and Development Commissioner of Special Economic Zone (SEZ) in SEZ, for services other than software; and
(iii)  An Authorised Dealer or Software Technology Parks of India (STPI) in DTA, and Development
Commissioner of Special Economic Zone (SEZ) in SEZ, for software.

Only RBI can clarify why they used ‘and’ as a connector in (i) and (ii) and why they used an ‘or’ in (iii).

For now, it means that for Software as defined in the notification, it is either an Authorised Dealer or STPI in the Domestic Tariff Area (i.e. units not in SEZ) and an Authorised dealer or DC SEZ in a Special Economic Zone.

Conclusion

The Software or IT and ITeS businesses will file the new EDF instead of the SOFTEX form after 1st of October 2026. The DTA units have an option to get EDF certified by Authorised Dealers (your bank) or STPI, and Authorised Dealers (your bank) or DC SEZ in a Special Economic Zone.

All services exporters other than Software must now file an export declaration. This is a change, as earlier services exporters other than Software (IT and IT-enabled) services did not need to file an export declaration.

The operating process is largely left to Authorised Dealers, hence the Banks’ digital transformation in this area becomes the key, and what process the Banks adopt will be critical to ease of doing in business as the notification on its applicability after 1st October 2026.

Disclaimer: The write-up here and ideas expressed should not be construed as legal advice. This is written with the industry practitioners’ approach on policy implications for the Software sector, for the purpose of benefiting the Industry members.