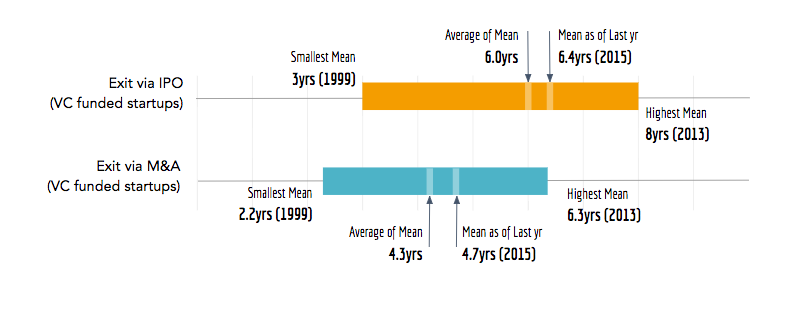
Manjunath Nanjaiah, Thiyagarajan(Rajan) & Sharad.
Story of an iSPIRT Volunteer.
Manjunath Nanjaiah, Thiyagarajan(Rajan) & Sharad.
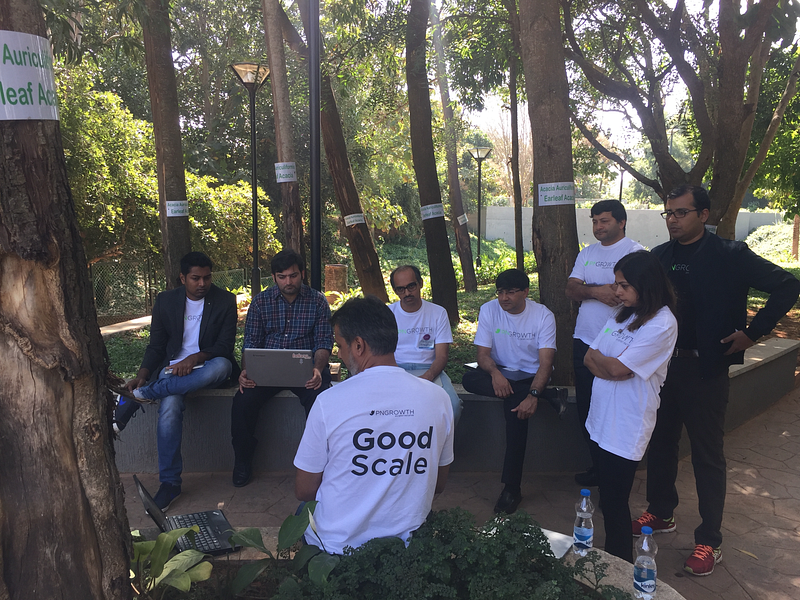
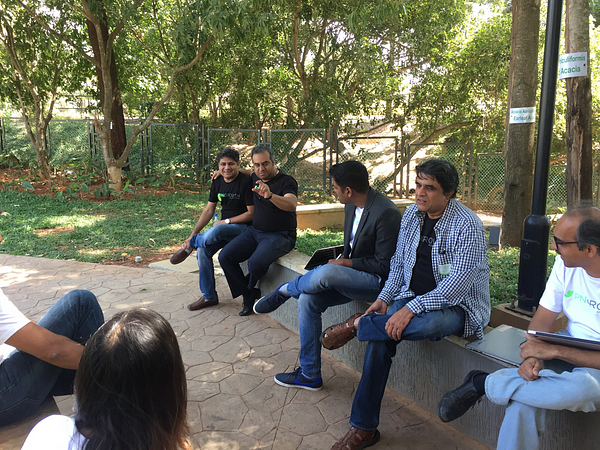
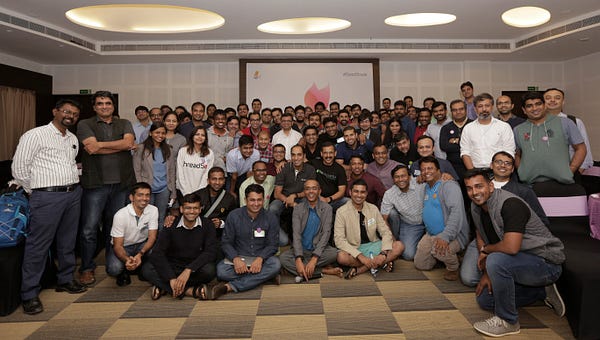
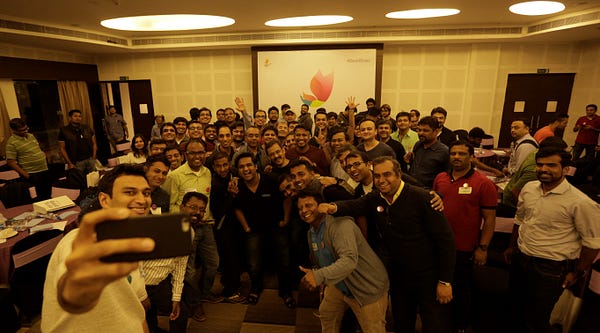
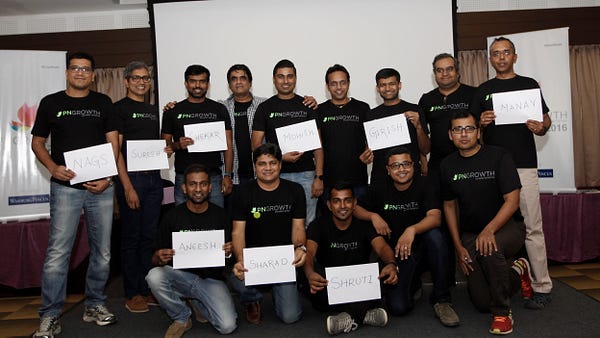
It was all about #GoodScale at #PNGrowth2016 !!

I participated as a volunteer this time around and missed the keynote in day one since I was busy in printing #MindFlip worksheets for 50 odd entrepreneurs. These entrepreneurs were handpicked by a very credible set of people who knows what #Scale means to B2B products.
Pallav and Shankar Maruwada did the priming by asking all the founders to reflect and redefine themselves within a framework that was designed carefully. Here not only they were asked to redefine who they are but were asked to open their heart and mind to play ping pong shooting game with co-participants sitting next to them. Learning to allow others become your mirror is a great way to identify your mistakes faster. These hard hitting peer challenge just bring the hidden self and does the world of good and the benefits will longer. Once they know who they are, they were told to pitch for a different context and at a different level. Mentors and peers played a critical role here and acted as an investor, prospective employee, customer etc.
When Phani talked about how he was lucky and all that happened around him at RedBus just happened and he just sailed through the wave. With all that humility he then explained if he had to present something like Girish, it will be something. The contrast was visible and it was beautiful as nature painted on a canvas. Girish spoke about #GoodScale he narrated the techniques that helped him to shape up Freshdesk. These techniques are not #GrowthHack these are practices that have been experimented, hammered and perfected. The honesty and ability to open up without ego, self-promotion was incredible to see.
Learning sales funnel from people like Aneesh, Suresh, Girish is like dream come true and Aha moment for many. These are something that can be practiced and implemented the next day !!
Manav re-iterated that it’s all about Sale-Sale-Sale for the founders to win. It truly amazing to listen how he closed big deals or key hires over cup-of-coffee, I personally loved the way Manav has navigated the journey by increasing his target market size with one step at a time. Solving one problem at a time and then moving to adjacent space which made it easier to traverse instead of starting big from day one.

The mentors were in no mood to get the feel-good emotion to sync deep inside founders, while some of them were in the go-kill-it mood, Sanjay Anandaram, and Sanjay Deshpande did a Jugalbandi and helped people to come down to earth from cloud 9. While everyone one builds a multi-billion dollar business it is also important to understand what the expiry date for the things that we do and then taking the smaller exit when appropriate does a world of good to the founder and as well as the country.
There were some discussions around “let go” — while good scale requires founders to realise it’s important to let go things and have other participate in growth, however depending comfort one could choose to hands-off-and-eyes-on model. Lots of participants participated in this discussion and shared how this could become the biggest bottleneck to scaling.

Building #ProductionNation is not an individual effort and is no less than #FreeDomFight for a country like India. People compare everything we do with #SiliconVally. However, I can’t imagine whether #PNGrowth is possible in #SiliconVally where successful founders will come and spend 3 days apart from spending days together in preparing the content and structure of the program during the last couple of months. The selfless attitude and ability to open their armouries to a group 70 odd startups are simply amazing to see.

Signature Club Resort at Brigade Orchards was amazing in the evenings. Hanging out with 50+ founders with DJ Music and beer gets even better. Ashish Tulsian and Vinod Muthukrishnan are shining star and we discovered them during last PNGrowth. After the heavy and long day, there is no better way than chilling with them. Their unique ability to hold a large group of people and make them laugh is just unthinkable and you can only relate to it if you have been part of the show before. This time the VC teardown in front of a VC was just the killer effect of the whole event !!

Hope this has shaken and woken up some of the founders and they will carry all that they got and move from #HappyConfused state to a 100 Million dollar or more startup in years to come.
I am so fortunate to witness this event. Great learning for me as well even though I was not able to sit through all the sessions. My biggest learning: everything has an expiry date and learning how to map that to what I do is key to success small or big !!

One more announcement to the stay-in-India check list has come from RBI with respect to registered under SEBI (FVCI) Regulations, 2000.
RBI has announced amendments to the Foreign Exchange Management (Transfer or Issue of Security by a Person Resident Outside India) Regulations, 2000, notified vide Notification No. FEMA 20/2000-RB dated May 3, 2000, as amended from time to time (Principal Regulations).
Sanjay Khan Nagra, iSPIRT volunteer talks about this announcement in the video embedded. Below. Also the main provisions and text is described in this blog below. Those interested in the original regulation may visit this page here.
As per the amendment notification referred to above, any FVCI which has obtained registration under the Securities and Exchange Board of India (FVCI) Regulations, 2000, will not require any approval from Reserve Bank of India and can invest in:
1. Equity or equity linked instrument or debt instrument issued by an Indian company whose shares are not listed on a recognised stock exchange at the time of issue of the said securities/instruments and engaged in any of the following sectors:
(i) Biotechnology
(ii) IT related to hardware and software development
(iii) Nanotechnology
(iv) Seed research and development
(v) Research and development of new chemical entities in pharmaceutical sector
(vi) Dairy industry
(vii) Poultry industry
(viii) Production of bio-fuels
(ix) Hotel-cum-convention centres with seating capacity of more than three thousand
(x) Infrastructure sector (This will include activities included within the scope of the definition of infrastructure under the External Commercial Borrowing guidelines / policies notified under the extant FEMA Regulations as amended from time to time).
2. Equity or equity linked instrument or debt instrument issued by an Indian ‘startup’ irrespective of the sector in which the startup is engaged. A startup will mean an entity (private limited company or a registered partnership firm or a limited liability partnership) incorporated or registered in India not prior to five years, with an annual turnover not exceeding INR 25 Crores in any preceding financial year, working towards innovation, development, deployment or commercialization of new products, processes or services driven by technology or intellectual property and satisfying certain conditions given in the Regulations.
3. Units of a Venture Capital Fund (VCF) or of a Category I Alternative Investment Fund (Cat-I AIF) (registered under the SEBI (AIF) Regulations, 2012) or units of a Scheme or of a fund set up by a VCF or by a Cat-I AIF.
iSPIRT believes these announcements have made Govt. Recognize the importance of opening up investment to promote innovative startups. Right now these announcements are limited to Startups recognized by DIPP. However, we hope in future they may be opened for all startups and an easy investment regime in Indian from foreign funding source.
Think about endgame, chess grandmasters do so to win.
Studies point out that chess grandmasters visualize the chess board state few steps away to a ‘winning game’ and make moves based on memory pattern that can lead to that board state and thus help them win the game.
Many startups however operate in a game where the rules are dynamic and change unexpectedly. An unanticipated flood of competition could sweep in, or the ground gets shaken underneath because of a regulation or policy change. Due to such unpredictability most of the founder’s move is extremely tactical, the focus is in on surviving and not getting killed as opposed to planning to grow like rabbits.
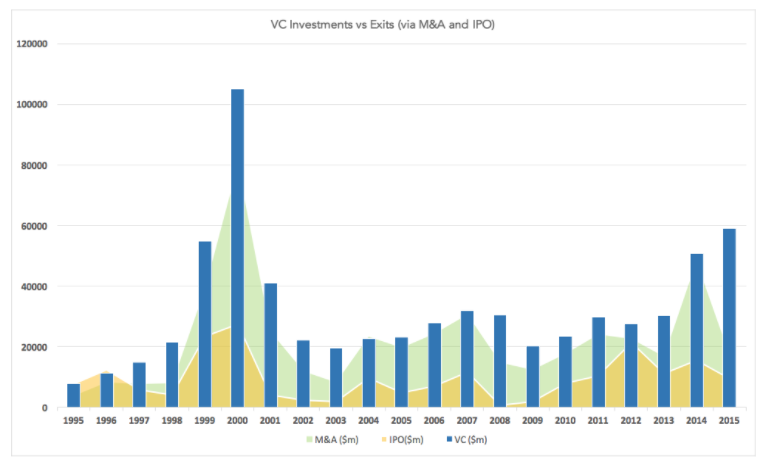
Data from 20 years of startups in US suggest mean time to exit is 4th and 6th year.

This is simply because If investors don’t do that then they can’t return the capital to their own investors (i.e limited partners) within the 10 year fund cycle.
Same data also reveals that after 1997 there has been more exit through M&A than IPO both in terms of count and value which means that it is more likely for a startup to have an exit via M&A rather than an IPO as the most likely route

In India with no IPO route, M&A is the most likely endgame
On decade long VC scale, Indian ecosystem is quite young and thus historical data is not available to compare however similar forces broady apply.
Also while scale can become large but technology market growth rates in India are not as fast the US. Add to this the fact there is no IPO market in India for the technology companies. Some efforts are underway to open it such as the new ITP platform by SEBI but nothing has kicked in practice. That makes M&A option all the more important to consider for an Indian startup founder.
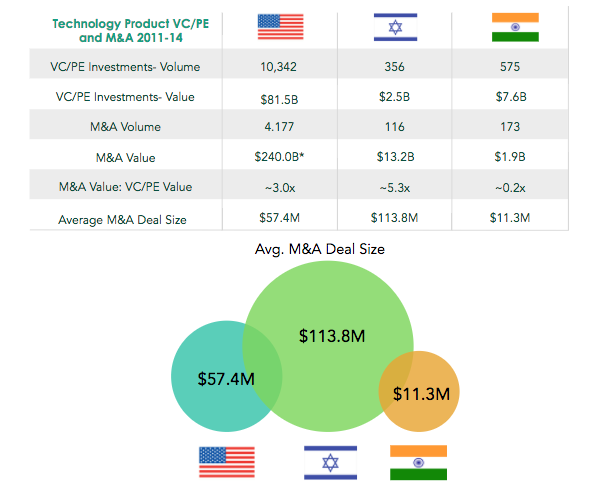
From limited data that is available about the Indian ecosystem we can that $14.5 billion of VC money has been invested in last 4 years and $2.5b of exits have happened in the same period spread over 300 deals. This ratio are still very skewed when compared to other ecosystem.

All of this build the strong case for why an Indian startup founder should think about exits via M&A
A reason they don’t think about it is because they don’t know much about exits or the playbook involved in doing that. Second likely reason could be that advisors actively discourage founders from thinking about exits by labeling them opportunistic and not being a visionary founder.
Paradoxically the right time to think about exits is exactly when an exit is not needed.
Founders should think about exit before they are forced to think about it
PS: Exit has a broader significance, applies to open source and even countries. Here is a talk by Balaji Srinivasan that illustrates the importance of exit as key lever of an healthy ecosystem
The November 8th announcement of demonetization of Rs 500 and Rs 1000 notes by Prime Minister Modi caught everyone by surprise. That was the intent. It is, however, widely expected that bank accounts, plastic cards and digital money usage will increase dramatically in the next 12 months. In other words, India will be pushed towards a cashless economy. The purpose of this piece however isn’t about the probability of a cashless economy happening; It is about the definite opportunity presented by the Indian kaysh-less economy. That is, the economy resulting from the removal of hair from people’s heads. India has been going kaysh-less for millennia. It is our kaysh that adorns the heads of Western celebrities like Lady Gaga, Beyonce, Naomi Campbell and any “Hollywood who’s been a mile of a first class weave” according to Mother Jones. It is Indian kaysh – renowned for its length, quality and strength – that is most prized in the making of wigs, weaves and hair extensions (“dry hair”) used by women in the West.
Annually, India exports about 1,300 tons of hair- 80 per cent of the world’s supply – contributing to about US$400 million in revenues and employing thousands in the collecting, cleaning and sorting activities. Our temples sell the best quality hair – 20-30 per cent of all hair is harvested in temples – while barber shops and women’s combs and garbage bins generate the rest. Temple towns like Tirupati in Andhra and Palani in Tamil Nadu are on the world map for their hair exports. In 2013, Tirupati alone generated Rs 200cr from e-auctioning of 106 tons of hair; 25,000 heads are shaved daily in Tirupati where over 600 hairdressers are employed including 50 female barbers. Rural women who get their heads tonsured have prized natural long hair because it is uncontaminated by shampooing and styling chemicals. The significantly less lucrative shorter men’s hair on the other hand is mostly for industrial use eg stuffing clothes, fertilizers and for extracting L-cysteine, an amino acid. It is worth noting that this acid is used in pizza dough and bakery products so spare a thought the next time you bite into pizza and actually find hair in it.
Indian hair is closest to Caucasian hair and is the most heavily priced thanks to it being “remy” ie single cut and orientation of the cuticle. The remy hair from India goes largely to the US and Europe while the non-remy hair goes to China.
The Indian kaysh-less economy can be a global multi-billion dollar market opportunity; Interestingly, Africa alone offers a US$6billion opportunity that Indian companies can target. If only we considered it as such and, instead of just being a supplier of the primary commodity, got into the higher value-added products of branded dry hair. Instead, even in kaysh, like most things that originate in India, someone else is actually harvesting the serious cash! China, on the other hand, generates $2billion from its supplying dry hair products by partly using Indian non-remy kaysh!
India’s domestic kaysh-less economy – as a leading supplier of the best quality human hair – can provide a very lucrative cash generating opportunity for Indian beauty and wellness companies.
With 1.25billion people, India’s original kaysh-less economy isn’t an hairy-fairy business; It is hair today and definitely not gone tomorrow. The country needs a Big Hairy Audacious Goal. All we have to do is say, “hair! Hair!” to that. Will we?
Playbook Round Tables were created with an intention to orchestrate the coordination and exchange of tacit knowledge. Thoughtful Founders acted as facilitators in this sharing of tacit knowledge. We call them Mavens. For them, their contribution to #PlaybookRTs was a labor of love. It is a selfless contribution to making India a Product Nation.
Thanks to the Founder Mavens, PlaybookRTs went on to become very successful. The topic coverage grew. However, we were not able to find Founder Mavens for topics like Design Thinking and Inside Sales. We wondered if we should look for Mavens who were not Founders. But we were skeptical if they would be animated by the Product Nation mission. And, even if they were, would they contribute selflessly in a pay-forward manner that the Founder Maven did? Would they sign the Maven Code-of-Ethics?
Then we ran into Deepa Bachu.
Her commitment to making India a Product Nation was there. Yet we wondered if she would be willing to pay-forward in PlaybookRTs. We knew this was not an easy call to make. After all, it meant forgoing workshop revenue from product startups for the foreseeable future. As we talked, we realized that Deepa’s dilemma wasn’t whether she should make this selfless contribution! Instead, she was worried if the PlaybookRT attendees would value something that was free!
This led to a couple of experimental PlaybookRTs.
And here we are! Deepa learned that Sometimes Free Is Valuable. And we learned that there are contributors to the product ecosystem who will put the cause before their business. We find that the Practitioner Mavens are as vested in the pay-forward model as Founder Mavens. We cherish and value both of them.
With inputs from my colleague Rajan.
A recent article by Andy Mukherjee, predicting the end of India’s IT industry has caused lot of commotion. Though, the ‘end’ is an exaggeration, the warning of the ground slipping is not new. The declining growth is owing to the rapid transformation in technology and Software Industry itself, globally.
The first Software policy of 1986, resulted into Software Technology Park (STP) scheme in 1991. Undoubtedly, the policy was highly successful with IT industry today accounting more than 9 % of GDP.
Despite diminishing growth, even after 25 years, old Software policy (1.0) of 1986 still prevails, with focus on IT services. A reworked IT policy 2012, is generic, remained redundant with no meaningful churn out for new age Industry.
Failure to capitalize on the capability built in last quarter century can have serious consequences. The onus lies with Ministry of Electronics and IT (MeitY). However, MeitY seems to be missing on following four issues.
One, Software is core, not IT enabled Services (ITeS). Two, not able to gauge the shift in fundamental industry structure globally from ‘services’ to ‘products’ and also ‘cloud’ based products. Three, not able to appreciate ‘national competitive advantage’ has moved up the maturity curve to ‘Innovation stage’. Four, a phlegmatic approach resisting shifting gears swiftly.
To address these strategic paradigm shifts, a Software 2.0 policy is needed with ‘product’ as focal to it. We are at least 5 years late in our action here. Let us delve here into the four issues and related actionable.
It is important to understand here, that the genesis of today’s IT Industry was ‘Software’. The empirical evidence highlights real horse power coming from Software. IT enabled services (ITeS) is a derivative or related sector that grew through a ‘pull through’ effect of various related determinants (R. Heeks 2006). This is true even when we cut through the industry’s maturity stages. The ‘core’ has to be energised for new paradigm.
The big sector level transformative shift is ‘Standardised Product’ taking the center stage. This cuts across the ready Software packages (small, modular or enterprise grade), SaaS, PaaS and mobile apps.
The only subtle difference which remains is, whether a ‘product’ is sold to the end-user as ‘goods’ or a ‘product’ is hosted by SaaS or PaaS producer to provision the ‘productised service’. Even IT services business now hinges at standardised ‘products’ for revenues.
For about a decade no one believed that Software policy 1.0 could make India a super star in Software sector. It is only after about a decade, researchers recognized that India, a developing country could become a follower nation in Software sector. This was in sharp contrast to other 2 rising countries in same period of late 1980s i.e. Israel and Ireland, who were ascribed as Industrialized nation by world bank even in that period among the 3Is.
Usually academic researchers have not been very successful in predicting or prescribing favourable industrial policy for a country. But, they have played an important role when we apply an established research for analysing a sector’s performance and understanding the needed strategic shift.
Also, the classical economics models of ‘comparative advantage’ do not fit well for a sector like Software which is replete with advanced factor conditions.
The most comprehensive model to deep delve into this search is Michael Porter’s theory of competitive advantage (The Competitive Advantage of Nations, 1990). It goes beyond the macroeconomic theories on competitiveness and also incorporates the aspects of business and industry with advanced factors such as technology & innovation. The “diamond” model is based on four main determinant categories viz. factor conditions, demand conditions, Related and Supporting Industries and Firm Strategy, Structure, and Rivalry. It also incorporates and interlinks two extra parameters of a) chance and b) Government policy. For India both these played a vital role.
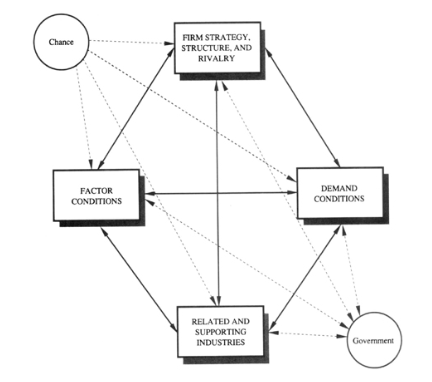
Porter’s Diamond Model. Source: The Competitive Advantage of Nations, 1990, Michael Porter’s (Kindle book, position 3060)
The national competitive advantage is based on the advanced level interplay of these determinants in the above diamond, network.
The model may lack in taking into account the new emerging factors of cloud and mobility computing. Yet, it offers a comprehensive and advanced postulation that can help understand the sectoral impacts.
Richard Heeks (2006), using this model concluded the competitiveness of Software sector of India. So also Bhattacharjee and Chakraborty (2015), further building on Heeks study. Richard Heeks (2006) says, “full diamond is not (yet) in place”. Whereas Bhattacharjee and Chakraborty (2015), recognize the full diamond in place. (Please see reference below at bottom)
Going beyond famous diamond model, the stages of development as postulated by Porter are more relevant to understand our readiness for ‘product’ stage. The stages in order are ‘factor driven’, ‘investment driven’ and ‘innovation driven’ (the last wealth creation points decline). R. Heeks (2006) finds ‘Investment driven’ stage in 2006. Bhattacharjee and Chakraborty finds ‘innovation’ having swept in the period 2012-2015.
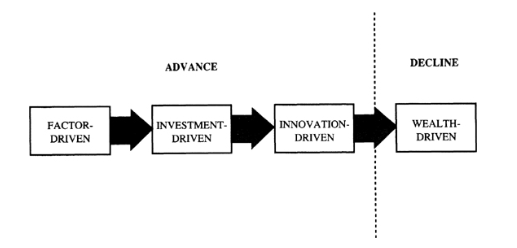
Stages of development. Source: The Competitive Advantage of Nations, 1990, Michael Porter’s from kindle book location 9634
“Govt. helping improve the quality of domestic demand and encouraging local startups” is representative of ‘innovation’ stage, says Heeks (2006). One can easily map here, the conditions arising to launch of StartupIndia policy 2015 and other accompanying developments.
Yet another symptom of ‘innovation driven’ stage is the domestic demand conditions undergoing a rapid change. ‘Digital India’, GST and UPI are not only concurrent, country scale demand generation programs, but also innovation boosters in domestic industry.
Porters, argues for a proactive role for cluster in National competitive advantage. The clusters enable innovation and speed productivity growth. The Silicon Valley and Israel’s Silicon Wadi are clusters that contribute to regional growth as well as making them as global brand. India has a distributed cluster model spread across various Tier 1, Tier 2 and Tier 3 cities. Bangalore, Hyderabad, Pune, Delhi NCR and Chennai being prominent.
India has enriched these clusters in the investment phase recognized by both the referred researches above.
In India, a mass of new age Software product startups has emerged touching wide array of industries. Advanced and specialized factor resources are emanating from the Software product development happening in the captive offshore center, R&D centers of MNCs or by outsourced product development (OPD) vendors, across all major IT cluster in country.
India therefore is poised for a phase 2 of Software Industry this time with product focus.
SaaS can be the next game changer for India. The national competitive advantage can be capitalized for creating a SaaS industry, and puts India in first three slot on global map.
Many Software as a Service (SaaS) companies like Zoho, Freshdesk are already global market place names, pitching for leadership in their own segments. It proves the power of SaaS to give edge in exports.
Out of more than 200 SaaS companies, number of them have incorporated outside, owing to the friction in doing global business from India. Software 1.0 policy doesn’t care for their issues. This loss can be plugged with Software 2.0.
India’s IT sector is strong enough to face changing technology challenges. It needs a ‘product nation’ based proactive strategy, that deals with ‘product ecosystem’ development, R&D, domestic demand boosters, frictionless trade and tax regime.
MeitY should rise to the occasion and announce a macro level policy framework, without wasting further time. Action plans (schemes, programs, incentives and institutional setups) can follow on need basis and in phased manner. This is how it happened in Software 1.0 policy as well. A new institutional setup is required. ‘National Software Product Mission’ should be setup urgently to cater to emerging Software product industry.
‘Software product power’ is cardinal to retaining global Software ‘power’ tag. Globally Software product market is estimated to be $1.2 trillion by 2025. India needs to target for 10-15 % of this. At home front, India needs to create ~3.5 million new jobs by 2025. Choices are limited.
iSPIRT has been working with MeitY for last 2 years to persuade them for taking a stand for a national level product industry while the service industry keeps growing. A nine point strategy draft is under consideration. But it has taken lot of time. In hardware product space, we have National Electronic Policy 2012. A National Policy on Software Product will replenish the industrial policy basket of MeitY and usher in growth in new areas of both domestic and international trade.
“Mere incremental progress is not enough. A metamorphosis is needed. That is why my vision for India is rapid transformation, not gradual evolution”, said Prime Minister at NITI Aayog recently.
We hope the announcement of the long pending ‘National Policy on Software Product’ (NPSP) will soon be forthcoming. Only then will PM’s dream of rapid transformation, become a reality to catalyze an “Indian Software 2.0 industry”.
1. Research article “Using Competitive Advantage Theory to Analyze IT Sectors in Developing Countries: A Software Industry Case Analysis”. By Richard Heeks, Development Informatics Group Institute for Development Policy and Management School of Environment and Development University of Manchester, Manchester, United Kingdom. http://itidjournal.org/itid/article/viewFile/228/98
2. Research paper, “Investigating India’s competitive edge in the IT-ITeS sector”. By Sankalpa Bhattacharjee and Debkumar Chakrabarti (Peer-review under responsibility of Indian Institute of Management Bangalore). http://www.sciencedirect.com/science/article/pii/S097038961500004X
3. The Competitive Advantage of Nations, by Michael E. Porter’s Free Press edition 1990
Recently GSTN invited application for becoming GSTN Suvidha Provider (GSP) under GSTN for enabling much awaited Goods and Service Tax. GSTN received total 344 applications. CEO GSTN reported in GSP workshop on 25th October that about 98 of these applicants are qualified for further evaluations according to them.
The GSP application process, when started created lot of confusion and concern on the eligibility criteria. The eligibility criteria are given here. One common concern was the financial capability criteria’s set by GSTN of:
iSPIRT had proposed that instead of a heavy turnover criterion the GSTN could have used a performance guarantee or a surety bond, both to ascertain the serious players and cover the risk of fly by night operators. This would allow some startups to take the risk and succeed to become GSPs.
The announcement did not clarify what is a GSP or what role will it have in the system.
A large number of interested startups through the GSP was about an application provider of product to file and comply with GST. Hence, the above criteria were considered as a barrier to startups. GSTN although off the record said they will accept application from all and will then evaluate who will be fit to become a GSP. This was however a very subjective approach, where GSTN will use their discretion to allow an enterprise to setup a GSP or not.
These concerns and doubts created confusion in minds of many startups, who have been looking towards the GST as an opportunity to innovate and implement in the space of tax compliance with added value with analytics and business intelligence.
It is subsequent to the workshop that many of these doubts have been cleared.
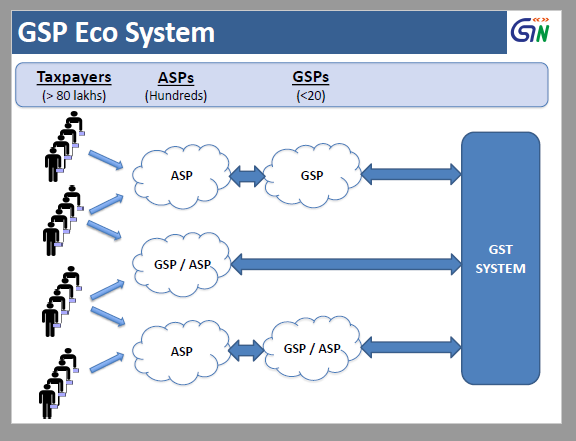
What finally turns out to be is that the GSPs are the middle layer infrastructure or utility provider or a API gateway to large number of GST filing apps. There may be a mix of GSP/ASP model where an ASP sets up a captive GSP. Even in that case GSP is merely a Gateway.
This blog is to answer some of the questions raised by participants in a Google Hangout conducted by Nikhil Kumar an iSPIRT volunteer. Additionally, it also answers other basic question with the related topic of GSP.
GSTN stands for Goods and Service Tax Network. It is a section 8, not for profit private company, with shareholding of Government of India, Government of States and UTs and financial institutions.
As a Special purpose vehicle(SPV), GSTN’s mandate is to establish, develop and manage the required infrastructure, systems, technology, partnerships and eco-system for implementation of GST.
GSP stands for GSTN Suvidha Provider. GSTN does not want to facilitate or connect to Goods and Service Tax filing application (called ASPs by GSTN and in this document) directly. This is for reasons of security and scale. Therefore, GSTN has planned a number of GSPs who will act as a middle layer between the ASPs or business and GSTN.
GSPs will facilitate the use of GSTN system to the businesses as well as products and application (developed by ASPs) to file the GST returns, match sales and purchase invoices to settle tax credits. The GSPs will hence help secure GSTN from direct exposure to users on internet as well as distribute the load in a large economy like India.
A GSP will hence act as a gateway that will pass enable the pass through of GSTN APIs (application programming interface) to and from users. There are three types of GSPs envisaged:
Source: GSTN website click here
This is how it is depicted in the above slide shown in GSP workshop. However, during the talk on GSP workshop it was mentioned that it will be mandatory for all GSPs to allow any ASP to use the GSTN APIs. Hence, it remains to be clarified by GSTN, weather the model 2 shown in above diagram means a Captive GSP and weather a captive GSP can deny access to third party ASPs to it’s GSP.
GSTN will sign an agreement with the selected GSPs which will govern the contractual relationship between GSTN and GSPs.
There is no final decision on how many GSPs will finally exist or be allowed. However, in the first phase, 98 GSP applicants would be allowed to participate in the technical evaluation. How many will pass or how many more will be evaluated has not been declared yet.
Application Service Providers are – Accounting Software, Invoicing Software, Point of Sale (POS) systems and other innovative applications that can enable businesses comply with GST. ASPs can work with multiple GSPs to enable GST for their customers.
Some ASPs may also have their own captive GSP. Dominant accounting and ERP product companies may have their captive GSP as this further opens up in future.
ASPs will have a contractual relationship with GSPs that they use.
As per GSTN, they do not want to control the ASPs and leave this for market forces to decide how many ASPs can be there.
ASPs are not a directly related party with GSTN. ASPs will have a contractual relationship with GSPs and GSTN will ensure the GSPs provide a free and fair access to ASPs to the GSTN resources.
GSTN , says yes they will evaluate on case to case basis. There is no defined policy. On eligible as per the criteria laid out it in the next phase
As per current information, GSTN will waive the first year charges for the GSPs. However, the GSPs would be allowed to charge the downstream ASPs. GSPs can also provide value added services on top of GSTN APIs and charge for them.
Again there is no define answer. The market will decide many things in future. For startups and small ASP players, it is important number of independent GSPs emerge for a fair and free market to exist.
As per announcement at GSTN workshop, the GSPs will not be allowed to share the GST data of businesses filing returns or sell the data to third parties. However, GSP can use this data themselves to create value added service offerings like business analytics and charge the individual businesses to do so. This means the data can be used to create a service offering for the given business only and cannot be cross sold to other parties. GSP will have to strictly adhere to data privacy clauses.
NSDL e-Governance Infrastructure Limited (NSDL e-Gov) is the depository (promoted by NSE, now running infrastructure and services for many mission mode projects of Government of India. NSDL is also slated to run the GSTN services.
NSDL will provide the neutral GSP services as an official independent GSP to ASPs. GSTN thus ensures that at least one GSP is ready for third party ASP providers get a GSP to serve the market.
As per GSTN answers to this questions, the GSPs will be legally bound to expose the GSTN APIs on a complete transparent pass through. However, GSP can provide additional rapper APIs for value add that they will like to build or management of their system.
As per GSTN response, Yes.
GSTN may conduct these in the future. However, none planned as of now.
One can use following resources of GSTN to get to more details.
At iSPIRT we are continuously involved with GSTN. Role of GST will be a game changer for India’s economy.
Our endeavour is that GSTN is able to offer a thriving platform for number of Product companies existing and new. It is also able to provide an open environment for innovation that can help some startups emerge offering valuable products to the business community.
[this blog is based on Google Hangout conducted on the topic by iPSIRT voluteer Nikhil Kumar, the inputs at GSP workshop conducted by GSTN on 25 Oct 2016 and group discussions with Bharat Goneka, Pramod Verma and Gian Franco Bonini of iSPIRT]
Most of our iSPIRT volunteers have demanding day jobs and yet they jump in to build public goods. They are animated by a cause and a sense of community. Some of them take their commitment to the cause so seriously that they let no task, however unsexy and mundane, get in the way of progress. Their do-what-it-takes approac
Take Rohith Veerajappa for instance. He stepped on the night 7th January 2016 to take charge of the 200 PNgrowth attendees boarding buses at Madiwala at 5:30am next morning. What was likely to be a chaotic and messy beginning turned out to be a wow experience. The boarding was smooth and efficient. He made the first touchpoint for attendees to a transformational bootcamp an out-of-norm experience. It was the best start that one could imagine.

Nobody asked Rohith to step in; he took the initiative on his own. Nobody was there to commiserate with him when he worked through the night; yet he was energised and upbeat. Nobody was there to demand a high standard from him; he set the bar himself. This uncommon ownership and determination is what makes him an iSPIRT volunteer hero.
With inputs from Gokul KS
True heroism is remarkably sober, very undramatic. It is not the urge to surpass all others at whatever cost, but the urge to serve others at whatever cost. – Arthur Ashe
iSPIRT invited select companies to leverage the IndiaStack API’s and collaboratively construct a pilot program, as a demonstrable proof of concept.
Broadly, the pilots were established to transfer the invented technologies and expertise to the market. In addition to creating sufficient and supportive infrastructure for technology transfer; to embolden entrepreneurs and businesses create profits based on intellectual property generated from these innovations, our pilot learnings were needed to help effectively address government, regulators and public institutions to seek their support for policy recommendations made by iSPIRT.
More specifically, the belief at iSPIRT was that for successful new technology venture, entrepreneurs and businesses should possess a combination of learning experiences, knowledge, self-confidence and skills to face challenges in various stages of commercialization process.
All participants to the pilot were carefully selected by examining their current business models, abilities to contribute to all aspects of IndiaStack, coexistence in a non-competing frame, investing in own resources (costs, effort, time) and above all for demonstrating their PASSION for technology and BELIEF that they will transform INDIA’s landscape for its people and businesses.
This pilot would not have been possible without the kind support and help of many individuals and organizations. iSPIRT is highly indebted to Khosla Labs for providing AUA, KUA services for free. eMudhra for being our eSign service provider, and for generously waiving fees while working to onboard all the partners in a compressed timeframe for the pilot. All our partners, namely Capital Float, Eko, Axis Bank, and Suvidhaa for enthusiastically supporting us, while setting aside their competitive instincts to collaborate and sharing learnings. And also to each of the iSPIRT volunteers for their guidance and constant supervision as well as for providing necessary information regarding the pilot & also for their support in commission to completion of the pilot in less than 90 days!
iSPIRT believes that by sharing the pilot learnings through the above publication, we will address aspects of entrepreneurship competencies and create the right entrepreneurial environment to produce innovations that are both technologically feasible and commercially viable.
iSPIRT would particularly like to extend its sincere thanks to CATALYST and Dalberg for the study and its dissemination.
Guest Post by Jaishankar AL, Tally Solutions
Whenever I have helped someone I believe their thanks is sincere and heartfelt. Can’t beat that wonderful feeling, so I do my best to make time and pay-forward.
Amongst the many that pay-forward, I was really intrigued by the iSPIRT community. A group of best-in-class entrepreneurs (and one could say even, celebrity entrepreneurs) coming together to share their knowledge with fellow and new entrepreneurs. With the hope to share some of my knowledge I started my engagement with iSPIRT running design thinking roundtables.
I have had the great fortune of having exceptional mentors teach me what I know about creating solutions that delight customers; design thinking – a mindset and a process to get inspired by customers, focus on trying things quickly and learn as you go to create solutions that will create awesome customer experiences. It was now my time to pay-forward. What started off as a pro-bono effort has brought me to today where I can proudly say that I am amongst the few privileged to be a part of this highly trusted iSPIRT Maven community.
Practitioners like me synthesize and create new-knowledge in a specialized field. This, in my case, is in Innovation & Design Thinking. A large part of such specialized human-knowledge, however, is stored as experience. It is tacit knowledge. The more you teach, the more you learn. Your knowledge gets refined almost everyday. So of course I wanted to share my knowledge fully expecting that I will be learning by teaching.
I was requested to do it pro-bono and sign into their Maven-code of Ethics which fundamentally is to commit for a pay-it-forward model, not expecting any payback in any form from any participating startups.
Do our audience even trust a Practitioner who is providing pro-bono services to be of high-quality, I wondered? We live in a culture where often quality if assessed with price and I wasn’t sure at first what I should expect. However, after just doing a couple of Round Tables I realized that trust is indeed created when people give selflessly in a pay-it-forward model. And, it is this very high degree of trust that allows entrepreneurs who are a part of the roundtables to provide open feedback to practitioners (aka Mavens) like me to continue learning and refining our craft. This is indeed priceless. Add to the this, the satisfaction of working for the cause of building a Product Nation together with many spirited Entrepreneurs.
Bangalore was the next stop for the iSPIRT product round-table around the theme of “Getting Traction for Software Products”. The goal of this round-table, hosted by Niraj Rout (Hiver/Grexit), Natwar Maheshwari (Around.io) Avinash Raghava and me, was to get peer feedback from a group of startups at a similar stage.
In this format, around ten participants meet and each one gets around twenty minutes to showcase their product and share their challenges. Everyone then gives feedback based on their experience. We met at the Hiver office at HSR Layout.

We have observed that most Indian product startups are not very comfortable with the self-service model, where the goal is to reduce frictionto product adoption and hence drive traction. With this format we get to talk about topics like automated sign-ups, on-boarding, customer success, content marketing, positioning and quality and nudge the participants towards this model. Most other round-tables talk about how sales can drive growth. Here, we focus on how products drive growth.
We have earlier done this format at Pune, Delhi, Ahmedabad and Mumbai before coming to Bangalore. Being an outsider, it was fascinating to see how the city of Bangalore was rapidly expanding. This magnet for migration has become a mess of concrete blocks, narrow lanes, traffic jams and angry cab drivers. But this is also where the startup ecosystem is thriving. The number of technology startups is astounding and there are many strong companies being built. At the round-table, we had a bunch of really amazing and diverse product companies.
The amount of startup literature available is almost unlimited, and every third person is self-qualified to dispense gyaan. At the round-table, we avoidgyaan by discussing specific problems. Some of the problems we discussed were:
At the end each one of us went back with at least one or two things we could work on.
What really stood out about this group was that this was a bunch of seasoned entrepreneurs. Almost everyone had real products. Their feet were firmly on the ground and were motivated to scale their companies to the next level.
I flew in to Bangalore a couple of days before the round-table to meet ERPNext customers and community members. It was both inspiring and humbling to meet users and developers who were working on a product we built. After all these years, I could see that the product had built a strong reputation and users were expecting a lot from us. Almost every conversation was around open source. Why? How? Are you crazy? I am certain that almost everyone who was uncertain about it before we met, had become an evangelist by the time our meeting was over.
On the evening before the roundtable, Niraj, Avinash, Natwar and I met at the Napoli Bistro at HSR Layout for dinner. Over pizza and soda, we chatted about the state of software products in India. While it was really nice to see product companies being able to survive and begin to prosper in India, there was almost no one taking moonshots, or outrageous risks, like Elon Musk. Most of the conversations we had were on the short term (survival) and medium term (growth).
On my way back to Mumbai, I reflected on what we were doing at ERPNext with open source and building communities. We believe that we are taking big risks, by breaking all the rules of how software products are built in India. In the context of the overall community it is important someone does that. With all the conversations I had over the past three days, I was convinced that we were on to something and we should take even bigger risks.
Whether we fail or succeed, is another matter. We need more moonshots.
It is not easy for Indian Software product companies to export products online and receive payments in India. This is true for both the downloadable Software product or Software as a Service (SaaS).
Experts say there is no legal or policy hurdle from RBI. Yet, there is friction. An Indian payment gateway service provider denies foreign currency cross-border transactions from India to a startups or small company. Only exceptions could be some large companies.
As part of ‘PolicyHacks’ at iSPIRT, we attempted to attend to the issue of recurring billing in a previous blog here. This blog is another continued effort in this direction. It is based on a discussion with experts from payment solution companies. Embedded below is a video discussion with Krish Subramanian, Cofounder of Chargebee and Kiran Jain of Razorpay.
The options available and adopted by most small Software product companies’ today are:
The option #1 above of using international payment providers comes with a heavy transaction cost. The services are not of same order as one can avail being in US or Europe.
So, option #2 and #3 becomes much attractive. This leads to exodus of Indian Software product company’s to USA, Singapore or Europe etc. India stands to lose in the game.
Krish mentions that, “the Indian companies are forced to move abroad to seek the frictionless experience in the payment part, where they allow month on month and do seamless upgrades and downgrades”. He further adds up, “Indian companies being in India do not get the level playing field, even when the strengths of product are very similar to a foreign product. Even using a solution like 2Checkout being in India does not provide seamless upgrade and downgrade. Hence, many companies go and incorporate outside”.
This problem, therefore, is one of the ‘biggest hurdle’ to the ‘stay-in-India’ concept for startups. It is vital that policy makers pay attention and remove friction to this problem for startups to believe in ‘India Story’.
Kiran Jain of Razorpay mentioned that the added attraction for Indian Software product company to move abroad is that, “an Indian company selling on international payment gateway from outside India does not have to comply with service tax”.
This is another level playing field problem. Being in India the Software product sales online is subject to service tax. On other hand being a foreign incorporated company and selling a B2C product the service tax is totally exempted. This is so in current policy framework and is going to stay same in the proposed GST framework.
Although, this is not directly related to the payment gateway problem, it does add-up to the exodus of Startups problem. This issue has been covered in an earlier blog here. It is a policy agenda item on list of taxation issues (of iSPIRT) to be addressed by Government of India and also an item on Stay-in-India checklist.
The cross-border online trade of Software product is directly a Payment Gateway issue. Let us further understand what are the underlying causes, policy issues, possible resolutions and suggestions.
Kiran says, “RBI came up with OPGSP guidelines in 2014”. And, “this policy allows the operation of International payment gateways”, that can facilitate both the foreign currency cross-border transactions and recurring billing. According to Kiran, many Indian banks have capability to provide platform which can accept international cards and multi-currency systems. Few banks support up to 17 different foreign currencies, though the settlement is all done in US dollars.
Why are banks not giving it? Kiran said that in last one year in USA, out of $28.33 trillion online transactions, $16.33 billion were classified as frauds. Indian banking system does not have a capability to incur such losses, “that is the threat to Indian banks”. This threat is the result of ‘returns’ or ‘charge-back’.
In case of delivery of downloadable Software product, at least there is a trail of transaction that can establish that the Software was really downloaded and if unsuccessful the Software can be delivered again. However, in case of services it may be difficult to handle the consumption trail at least in B2C transactions. In B2B transactions, such problems normally do not arise.
Hence, handling the risk of returns and charge-backs is the problem to solved. Solving this will encourage India banking systems to offer free and fair cross-border international payment gateway services.
Large players by virtue of volume or by offering a risk covering instruments can easily avail the service from banks themselves.
Small and Medium players can use payment aggregators. PayPal and 2Checkout are nothing but aggregators. Thy have infrastructure built in USA. In India they provide services under OPGSP guidelines. Their relationships with issuing banks in USA enables them to provide services in India.
Kiran says, “as on date we have many aggregators in India”. But, “we have not seen any Indian aggregator moving to US and partnering with banks like Wells Fargo or Worldpay”, who could build “an infrastructure trail in US and bring it to India and start providing cross-border payments”.
This will be a powerful option according to Kiran. This option can be used to ease out cross-border multi-currency payment system aggregation. This will give exporters alternative to PayPal and 2Checkout etc.. This will also reduce transaction costs by at least 30%. Now, an Indian merchant pays 4 to 6% plus the currency conversion costs as a compared to the 2.9% + 30 cents per transaction in USA.
The other advantage of Indian aggregator with US infrastructure will be the better understanding of the Indian merchants and the risks involved. Hence, better placed to manage the risks. “Today PayPal looks at every merchant as risky merchant”, says Kiran. The Indian players can have option of either aggregating the merchants on PayPal model. Or offer facility directly to mid and large players. In later case the entire risk engine is managed by the aggregator. The risk engine will take care of detecting the fraud cards, stolen cards, charge-backs cards as these will not be the capability of a merchant.
In the aggregator model, it is possible to play on volumes by on boarding a large number of small and mid-size merchants. This way an aggregator can easily go to a bank and say my charge-back to sales ratio is just about 1.76%.
Kiran further adds that as an alternative risk mitigation mechanism an Industry body could register small and mid-size Software product companies (merchants) and provide some kind of a certified credit rating. This could help banks and aggregators to assess the risk associated with the individual merchant.
Krish feels, a Govt. body like MSME could build a registration system of merchants with past history, people involved etc. (this could be like extending the Performance and Credit rating scheme of MSME). “This could act as a KYC”, says Krish for the aggregator, payment gateways and banks.
Are there Indian Aggregators offering such services?
As mentioned above, banks offer services in a limited way to large merchants. Aggregators like RazorPay also provide services but again with conditions attached.
Kiran says,“Razorpay provides the services on selective basis. We do not offer the option of card details to be held by merchants”. He further informed that merchant account with many charge-backs are suspended and that cases with one-off charge types may be allowed.
So, there is conditional availability of Indian service providers of cross-border online payment gateways.
“It is a crying shame if many startups still incorporate outside India just to get a level playing field”, says Krish Subramanian. He also listed following observations:
iSPIRT views on the overall situation on the given problem and present policy status are as follows:
MeitY can incorporate enabling policy measures in National Software product policy and offer an Indian Software product company registry that has an inbuilt mechanism to ascertain and certify a Software product company’s credibility. Also financial instrument like an Industry corpus fund could provide a common bank guarantee, that can be backup with surety bonds from individual product companies for a defined threshold.
In a digital world order, cross-border trade is going to be highly dependent on easy availability of international payment solutions. Indian merchants able to scale their international trade with ease is vital for India to be retain leadership in Software trade.
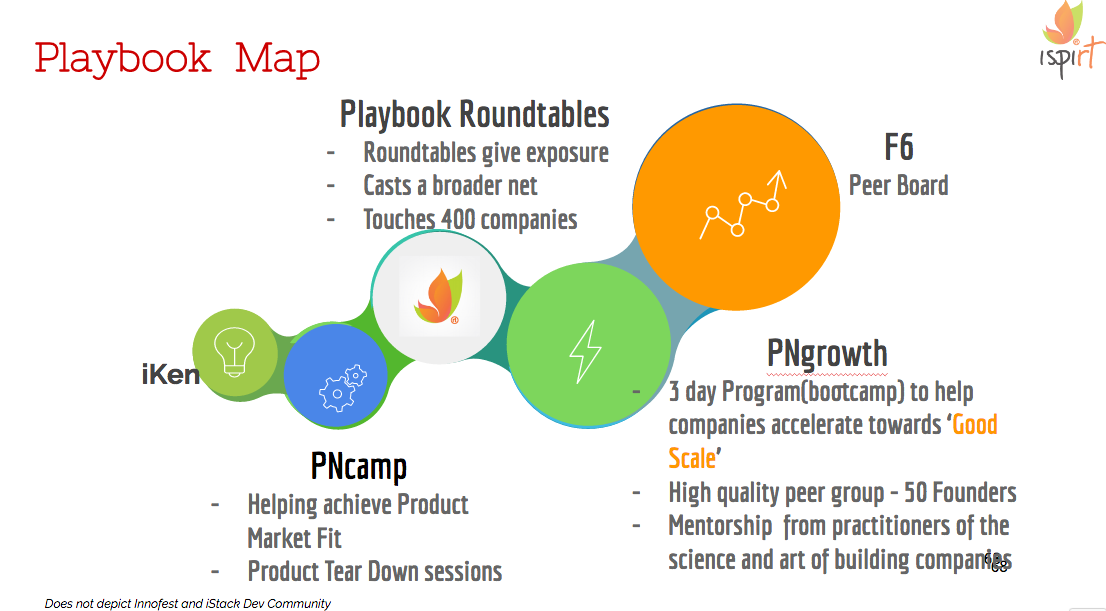
Playbook in iSPIRT denotes entrepreneurial learning meant for Indian software product startups to become world class and be successful.
Roundtable is a format of learning intended for startups that have reached a happy confused stage. In this format 8-12 non competing startups are brought together to discuss deeply on a topic that holds them from jumping to their next level.A facilitator, who is an in the saddle entrepreneur deep dives on the topic by becoming metaphorically naked and shares his experience and gets a peer discussion going on the topic.Coaching including peer coaching happens through multiple mode – judgement of the discussion (VC mode), sharing experience (Sage on Stage), being a mirror (Guide by the Side). Playbook Roundtable tend to be more of the last category of mirroring.
Think of this as group study for 7th class students in an age where there no school & teacher and one has to pass the 10th standard board exam. Some one who has done that leads the group study.
Playbooks have a longitudinal impact so they are tracked via an input metric. At the end of every roundtable session a Net Promoter Score (NPS) is calculated via survey, the average NPS score of last 85 roundtable that were held is about +80. (iPhone as a product has an NPS of +71).
Roundtable was initially architected by Shankar Maruwada, Ashish Gupta, Vivek Subramanian & Aneesh Reddy. Some learnings from past roundtable are captured here
Key organizing principles behind creating playbook roundtables
I have had the privilege to shadow about 40 of 85 roundtables that have happened in last 3 years. If I describe it as saying that gold dust of the tacit knowledge gets shared it won’t be an exaggeration. Chatham rules apply in a roundtable i.e. to protect the safe environment no quote is attributed to a person. However this deck those captures some of the discussed tacit knowledge as directives
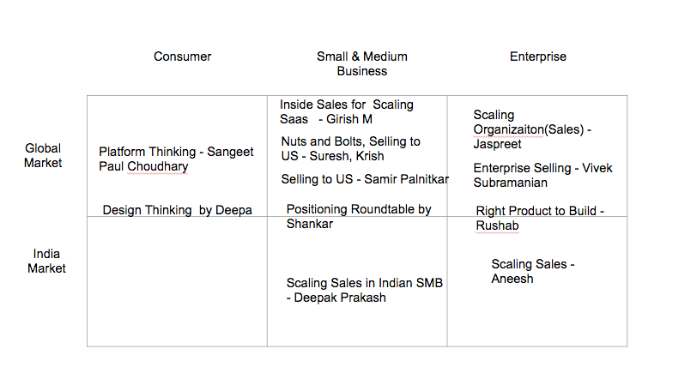
A good mental model to decide which roundtables can be used from the market map

Check details at the events section in PN blog
Playbooks is more than roundtable
The initial focus of Roundtable was happy confused product startup founders a later realization was that playbooks will need to extend across the spectrum of entreprenuership lifecycle.
kindergarden > discovery (1st to 7th std) > happy confused (7th std) > pre-scale (10th std) > pre-growth(pre college)

Some of these additional formats emerged
Playbooks sets down one of the most critical foundation layer for India to be product nation.
Close to about 15 founders gathered on 1st October at the small and cozy office of AdPushup to participate in a Playbook Roundtable on Content Marketing. This was Ankit’s first playbook with iSPIRT and he did a phenomenal job.
AdPushup is a SaaS company that helps web publishers increase their ad revenue by letting them test and optimize their website’s ad layout. Their expertise has been content marketing, and Ankit shared several details of their experience, learning and strategy which have helped AdPushup become a leader in content marketing in the AdTech software space.
Ankit stressed upon the fact that when starting in inbound practice, founders themselves need to get involved. Inbound is a long term game and requires a lot of patience and perseverance. By getting their hands dirty, founders understand the intricacies involved in inbound and thereby are build the right team and culture.
The first step in building your inbound strategy is to put together a buyer persona. It is basically a description of your ideal customer – someone who will directly benefit from your product or service. Creating content around and for them is what will get you more traffic, engagement and a sustainable growth. You could identify buyer persona by:
A typical buyer persona will consist of the following:
A buyer persona will help you identify the kind of content and channels you need to focus on in your inbound strategy.
Content CreationThere are two types content that founders can focus based on their industry and product:
The tone of the content should be educational and non promotional. Create content only keeping in mind – “is this helping someone solve a problem?”. At AdPushup, their target audience is long form bloggers and large web publishers. They write content which either informs them or helps in dealing with a painpoint (e.g. blogging tips, how to get more subscribers, how to get more traffic, user psychology, increasing user engagement, among others).
Each content piece should be:
Content should have:
Content ideas mostly come from:
Nail the headline of every post that you publish and you will have won 70% of the battle. If your headline doesn’t inspire confidence, interest, excitement or any sort of emotion then readers wont click on it. Then even though your content might be brilliant and relevant, it will just not get the importance it deserves.
An important rule of thumb to remember is that whoever is the content creator – allocate 50% of time in creating content and the rest 50% in distributing it.
Some of the channels for content distribution include:
When you join communities on social networks, regularly engage with their members. This helps when you have to share your content there and not come across as a spammer.
Reddit is infamous for being ruthless with spammers and self promoters. So the only way you come across as neither is by providing all the value right there in the community post and add a small link in the end which says something like – “to read the full post, here’s the link” (and provide the exact url, not bitly or any short links). Provide the entire outline right there. Anyone reading it should only click on your post when they know exactly what is in the content and they would still want to read it.
Whoever you mention in our post, product or person, make sure to send them or the relevant team members an email telling them about the mention and encourage them to share it on their social media. Most people do actually share if you ask them. Also, it helps if you are relatively well known and the content is really well written.
Look for guest posting opportunities because they are an effective way to make your presence in the industry. And guest post only on sites that are relevant to your audience, have a very high volume of traffic and well respected (e.g. HubSpot, KISSmetrics)
Once you have created content and distributed, it is imperative you capture details of the readers. You could devise several ways to do that:
Make sure your email marketing is sorted out. Put pop-up email capture boxes (and similar lead capture forms/boxes) in your blog to encourage visitors to convert into subscribers. Once you have a decent number of subscribers (300+) and are pushing content out regularly, start rounding them up and email them to your subscribers in the form of a ‘weekly newsletter’.
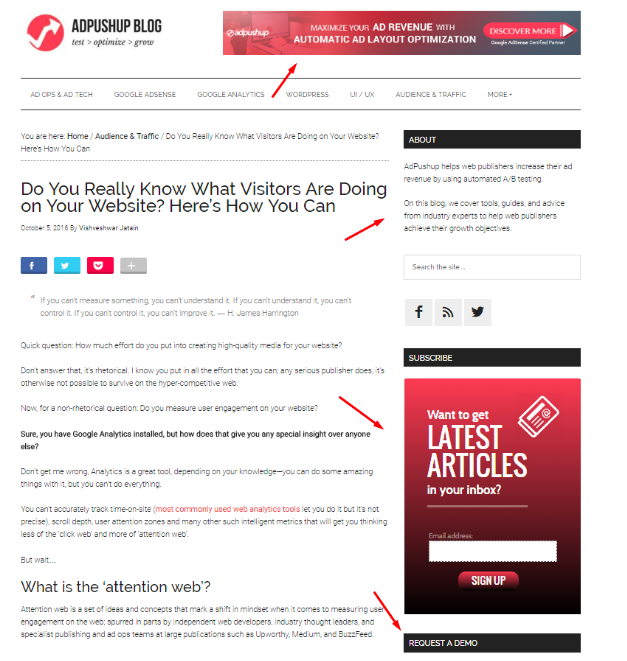
Here is a screenshot of how AdPushup uses its content to capture user details.

Finally it is important to measure and analyze your inbound activities. As Ankit puts it, “Inbound is a continuous rinse and repeat process”. Few key metrics to track include:
Once you have a sufficient success in measuring ROI – cut out what is not working and concentrate only on what is getting results. And always keep creating hypotheses and rigorously testing them. You never know what product or customer insight you might stumble across.
Guest Post by Rajat Harlalka, Bellurbis